• Skip to main content
  • Skip to secondary menu
  • Skip to footer

Market Research Media

taking uncertainty out of decision making

  • Sponsored Post
  • Domain Marketplace
  • Publications
  • Technology Desk
  • About
    • How to Conduct Market Research, a Practical Step-by-Step Guide
    • Methodology, How Market Research Media Works With Numbers
    • Why Is Market Research Important, Seven Decisions It Changes
    • Reports
    • How to Conduct Media Market Research, Audiences, Ratings and Ad Spend
    • How to Conduct Social Media Research, Listening, Sampling and the Limits of Platform Data
    • How to Conduct a Market Research Survey, From Sample Size to Question Wording
  • Contact

Adobe FY2025 Results, $23.77B Revenue, $25.2B ARR, Over $10B Cash Flow and FY2026 Guidance

December 11, 2025

Adobe’s latest numbers sketch a company shifting from “creative software incumbent” to “AI-native subscription machine,” and the market is likely to treat it that way—less like a discretionary software vendor, more like a hybrid utility with embedded AI monetization. The headline is the company’s record FY2025 performance, but the deeper signal sits in the durability of ARR growth, the discipline on margins, and the very deliberate reshaping of reporting lines ahead of FY2026. That kind of repositioning almost always telegraphs internal confidence in the revenue model.

The quarter itself—$6.19B in revenue, +10% YoY, with non-GAAP EPS at $5.50—lands right inside the company’s cadence throughout the year. What stands out isn’t the top-line growth (steady, not spectacular) but the mix behind it. Digital Media drove $4.62B (+11%), while Digital Experience added $1.52B (+9%), and both sides quietly showed that AI-infused tiers are doing exactly what they’re supposed to do: expand ARPU without creating major churn waves. The $22.52B RPO and 65% cRPO give Adobe multi-quarter visibility most software companies would kill for. Cash flow was monstrous—$3.16B in Q4 and over $10B for the full year—meaning subscription health isn’t just theoretical; it’s throwing off cash at scale.

The full FY2025 picture reinforces this pattern. $23.77B in revenue (+11%), $25.20B in ARR (+11.5%), nearly $11B in non-GAAP operating income, and 30.8M shares repurchased suggest a business that’s both maturing and becoming more predictable. Adobe’s cost discipline is visible in the stability of operating margins—even with heavy AI R&D spend and the fact that sales and marketing rose by ~$700M YoY, the company maintained non-GAAP margins above 45%. The only real blemish is the cash balance dropping from $7.6B to $5.4B due to buybacks, but that’s a strategic capital allocation choice rather than a liquidity concern.
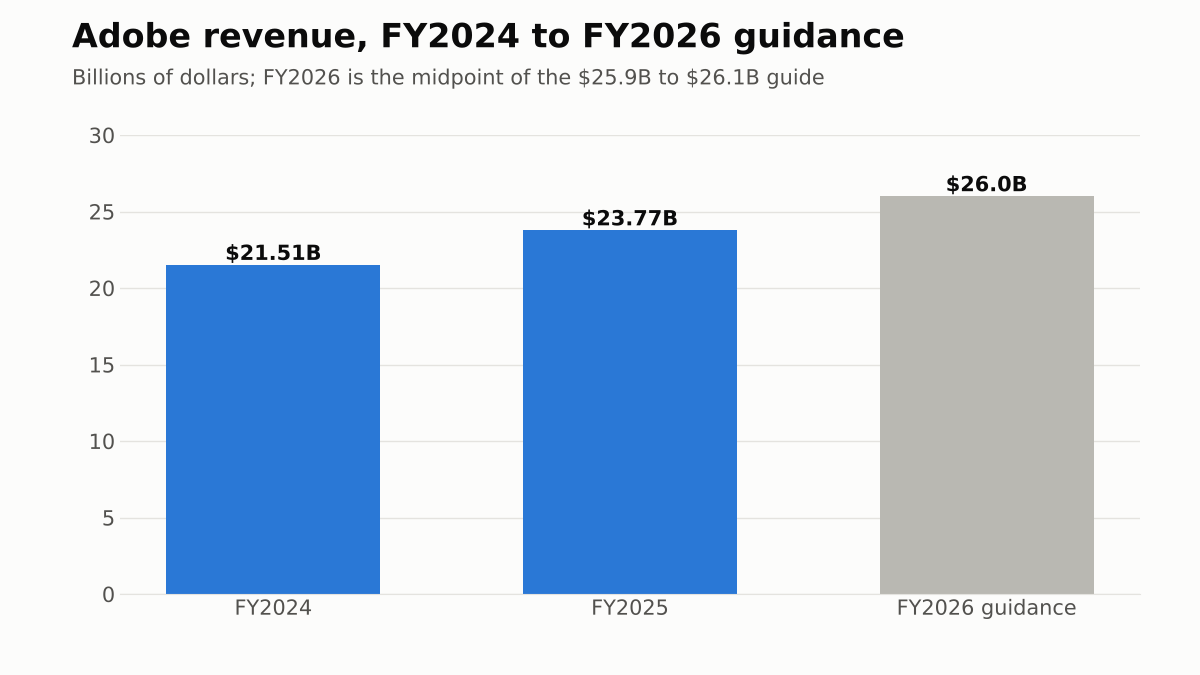
Adobe annual revenue, FY2024 $21.51B, FY2025 $23.77B, FY2026 guidance midpoint $26.0B

And here’s where things get interesting: Beginning FY2026, Adobe is changing how it reports. Rather than segment-led reporting centered on Digital Media vs Digital Experience, the company will shift emphasis to customer-group subscription revenue and total-company ARR growth. That’s a structural pivot. Adobe wants analysts to track the health of its subscription base directly, not the legacy segmentation inherited from the Creative Cloud and Experience Cloud eras. The choice signals a belief that AI-driven bundles will increasingly blur old boundaries anyway. When a company preempts that shift, it usually believes the model has legs for many years.

FY2026 guidance reinforces that confidence. Adobe is targeting 10.2% ARR growth—solidly double-digit in a world where many SaaS players are slowing to mid-single digits—and $25.9–$26.1B in revenue, plus non-GAAP EPS of $23.30–$23.50. Those numbers essentially argue that AI upgrades, cross-sell, and a broader addressable market (especially via Business Professionals & Consumers) will do more heavy lifting than macro conditions will take away. And with non-GAAP operating margin guided at 45%, Adobe is promising to maintain profitability even while building out the next generation of its AI platform. The fixed 18% non-GAAP tax rate helps support EPS, but the operational efficiency story is real.

From a balance-sheet perspective, debt is up to $6.21B from $4.13B, but Adobe’s scale, interest coverage, and cash flow make that manageable. Goodwill ticked up slightly, hinting at some tuck-in M&A, and Semrush’s $1.9B acquisition (excluded from guidance until closing) fits perfectly into Adobe’s ambition to own more of the marketing visibility stack. Once integrated, Semrush should open new pathways between content creation and content performance—potentially a meaningful upsell path.

Adobe did lose about $2.5B in quarterly cash to buybacks, which is aggressive but signals a management team betting heavily on long-term valuation. Treasury stock ballooned from -$37.6B to -$48.8B, a reminder that Adobe treats buybacks as a core tool for supporting EPS expansion.

The broader narrative is simple: Adobe is leaning hard into a world where creativity, productivity, documents, and marketing operate inside AI-driven workflows—and it intends to be the platform that orchestrates all of that. Record ARR, record cash flow, sticky subscription cohorts, and freshly tightened reporting structures all point to a company intentionally easing investors into a long-duration AI story.

The downside risks are still present—AI disruption, competition from both incumbents and challengers, macro sensitivity, and regulatory scrutiny—but Adobe’s numbers suggest those risks are being absorbed without impairing the model. The shift from product revenue to subscription revenue is nearly complete; the ARR engine is humming; and the company seems intent on acting like a premium compounder.

Adobe continues to trade not like a cyclical software vendor but like a high-quality recurring-revenue infrastructure asset. For analysts, that means valuation debates will increasingly center on ARR durability, AI monetization velocity, and operating leverage rather than unit sales or product cycle timing—a subtle but meaningful shift for how the market will price ADBE moving forward.

Filed Under: Media Business Tagged With: ADBE, Adobe, Creative Cloud, earnings

Footer

Recent Posts

  • China US Treasury Holdings 2025-2026, Latest Data Shows an 18-Year Low of $564 Billion
  • Counterfeit Goods Market in 2026, the Real Numbers Behind the Trillion-Dollar Claim
  • NoSQL Databases in 2026, MongoDB Speeds Up While PostgreSQL Absorbs Everything Else
  • US Military Drone Spending in 2026, From Reaper Orbits to Hundreds of Thousands of Cheap Drones
  • Military Laser Weapons in 2026, Iron Beam in Service, HELIOS at Sea and the Army’s First Laser Program of Record
  • Online Video Trends in 2026, YouTube Takes 15.8% of US TV Time and Microdramas Go Mainstream
  • US Federal Cybersecurity Spending in 2026, a Smaller CISA and What It Means for Vendors
  • Global Cloud Computing Market in 2026, $168 Billion a Quarter and Growing 55% on AI
  • Deep Packet Inspection in 2026, Blinded by Encryption in the Office and Thriving in Russia and Iran
  • Netflix Creative Decline in 2026, Why the Formula Problem Now Shows Up in the Numbers

RSS feed: Market Analysis Market Analysis

  • Anthropic Shares Rise 21% on IPO Debut, but the Wider AI Market Sends a Different Signal
  • Quad9 France Exit Turns DNS Blocking Into an Infrastructure Market Risk
  • Robot Market Fight Heats Up as US Orders Jump 25% and Chinese Humanoid Makers Lose CES Visas
  • Anthropic (ANT) Prices at 83 Dollars and Wall Street Wraps It in 2x ETFs and CFDs Within Days as Cantor Explains Its Nvidia Hedges
  • Hormuz Risk Gauge Falls to 63.8 High as the Dubai Premium Vanishes While Tanker Attacks Keep Coming
  • China Turns AI Model Distillation Into Industrial Policy and Weakens the Reach of US Chip Controls
  • AI-Found Software Flaws and the Rush to Patch Them Are Now a Market Risk After a Week of US Outages
  • Ohio Voters Put $17 Billion of Amazon Data Center Spending at Risk as Local Bans Spread
  • US Remote Access Chip Rule and FCC Optics Ban Squeeze Southeast Asia Data Centers and Nvidia China Exposure
  • Microsoft Puts Word, Excel and PowerPoint Inside Copilot and Turns Office Into an AI Front Door

Media Partners

  • Analysis
  • Technology Conferences
  • OSINT
  • Defense Market
  • Cybersecurity Market
  • Event Calendar
  • Calendarial
  • Opinion
  • 3V
  • Media Presser
  • Exclusive Domains

Copyright © 2026 Market Research Media | Terms of Service | Privacy Policy | Supplier Disclaimer | The Website Coded and Designed by SoftDev Studio

Media Partners: Technologies | Photography | Referently

We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept”, you consent to the use of ALL the cookies.
Do not sell my personal information.
Cookie SettingsAccept
Manage consent

Privacy Overview

This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary
Always Enabled
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
CookieDurationDescription
cookielawinfo-checkbox-analytics11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional11 monthsThe cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance11 monthsThis cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy11 monthsThe cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytics
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.
Others
Other uncategorized cookies are those that are being analyzed and have not been classified into a category as yet.
SAVE & ACCEPT